
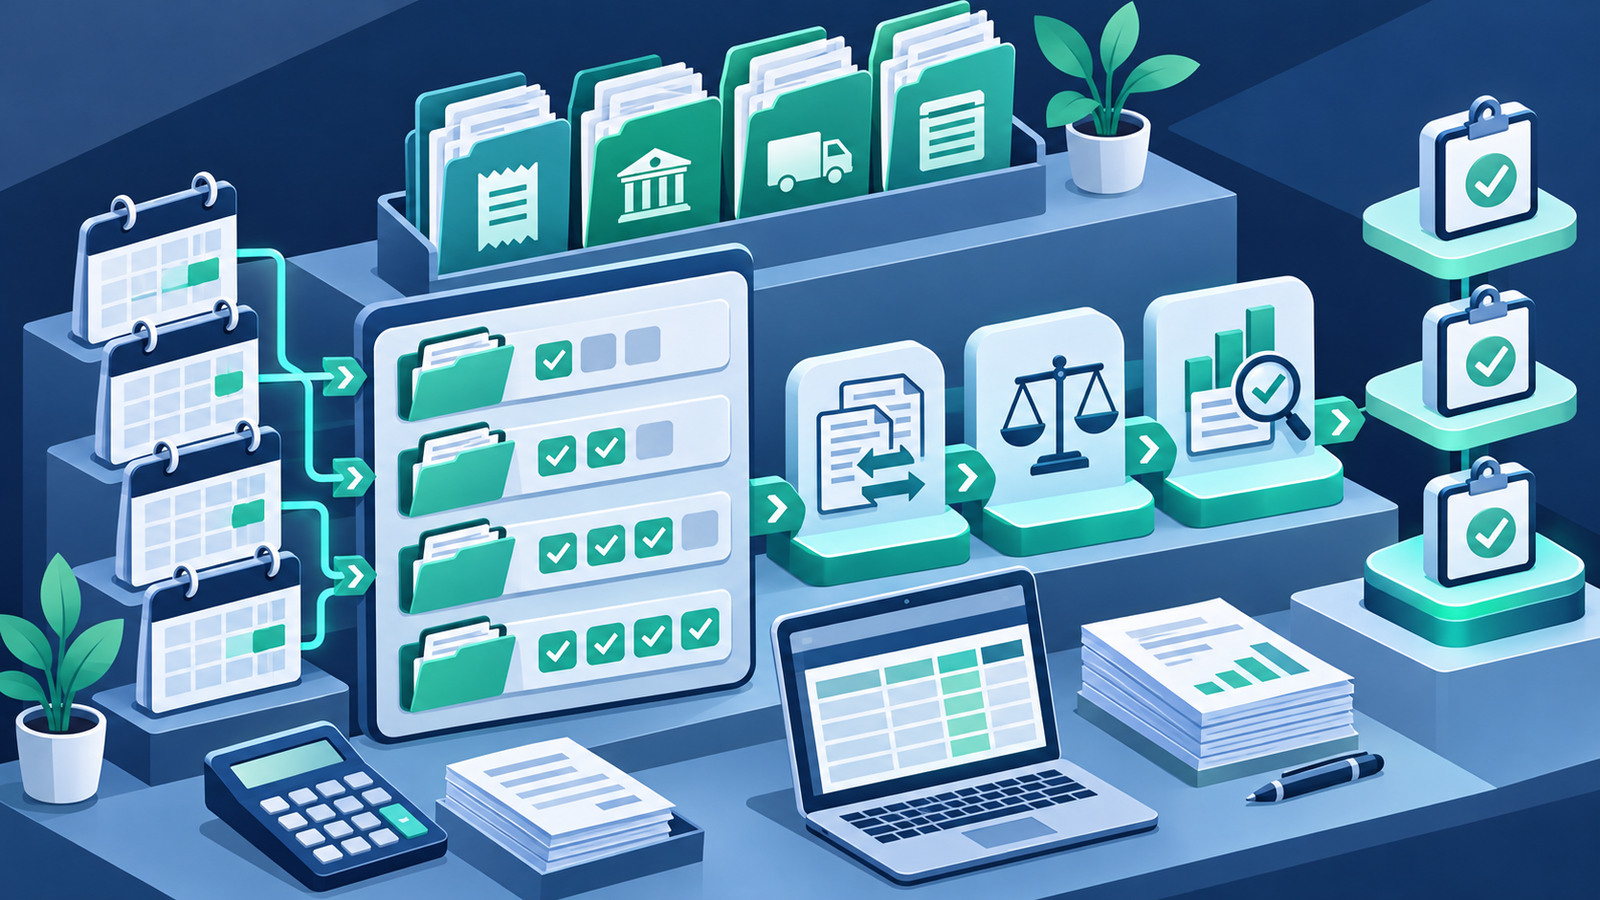
Direct answer: Overdue BAS catch-up fees are easier to control when work is staged: confirm the period register, test evidence readiness, reconcile one representative period, price the remaining periods using disclosed assumptions, then separate preparation, review, lodgement and post-lodgement payment actions. A single lump sum should still explain what happens if records are incomplete.
This general guide is for Australian small-business owners, including Epping, Melbourne and Victoria. Confirm current rules and software settings for your circumstances.
What should happen before a fee is finalised?
List every outstanding period and identify available bank, sales, purchase, payroll and GST evidence. Check the ATO account for required periods. A period count alone does not show whether the work is routine or requires reconstruction.
Why can a pilot period improve the estimate?
Review one representative quarter to identify transaction volume, missing documents, reconciliation gaps and prior errors. Use the result to update assumptions for later periods rather than promising that every quarter will take the same effort.
Which stages should be priced separately?
Distinguish evidence collection, bookkeeping cleanup, reconciliations, BAS preparation, technical review, owner approval, lodgement and payment follow-up. Confirm which work requires a registered BAS or tax agent and check the TPB public register.
What should trigger a revised fee or pause?
Examples include undisclosed bank accounts, missing payroll records, unreliable opening balances, material GST errors or a new period added to the register. Explain the trigger, evidence and approval needed before continuing.
How should completion and payment actions be recorded?
Keep the approved BAS, lodgement receipt, account status, amount due and payment owner. Lodgement does not itself pay a liability or establish a payment arrangement.
What belongs in the practical checklist?
- ATO period register checked
- Evidence readiness by period
- Representative period tested
- Cleanup and BAS work separated
- Assumptions and volume limits stated
- Variation triggers explained
- Reviewer and registered practitioner confirmed
- Lodgement and payment actions recorded
What could this look like in practice?
Hypothetical example: A hypothetical Victorian contractor has six overdue quarters. A pilot quarter shows missing payroll records and an unreconciled bank account, so the provider prices cleanup separately and agrees a stop point before BAS preparation. The example is invented and assumes no ATO outcome.
What do business owners ask?
Should every overdue quarter cost the same?
Not necessarily. Transaction volume, evidence quality and unresolved errors can differ by period.
Can a fixed fee still include variation rules?
Yes. State the records, volume and period assumptions plus the approval required for extra work.
Is payment-plan work automatically included?
Do not assume so. Separate lodgement, payment advice and any authorised ATO contact in the scope.
Where can you continue?
Read the live parent guide, review service information, use the related incomplete overdue BAS catch-up guide, and explore the TNS Accounting homepage.
Which official sources were checked?
- ATO: GST records for BAS
- ATO: correcting GST errors
- ATO: BAS due dates and paying
- TPB: public register
Published by TNS Accounting. Official sources checked 21 November 2026. Rules, guidance and software features can change; confirm the linked sources before acting.






