
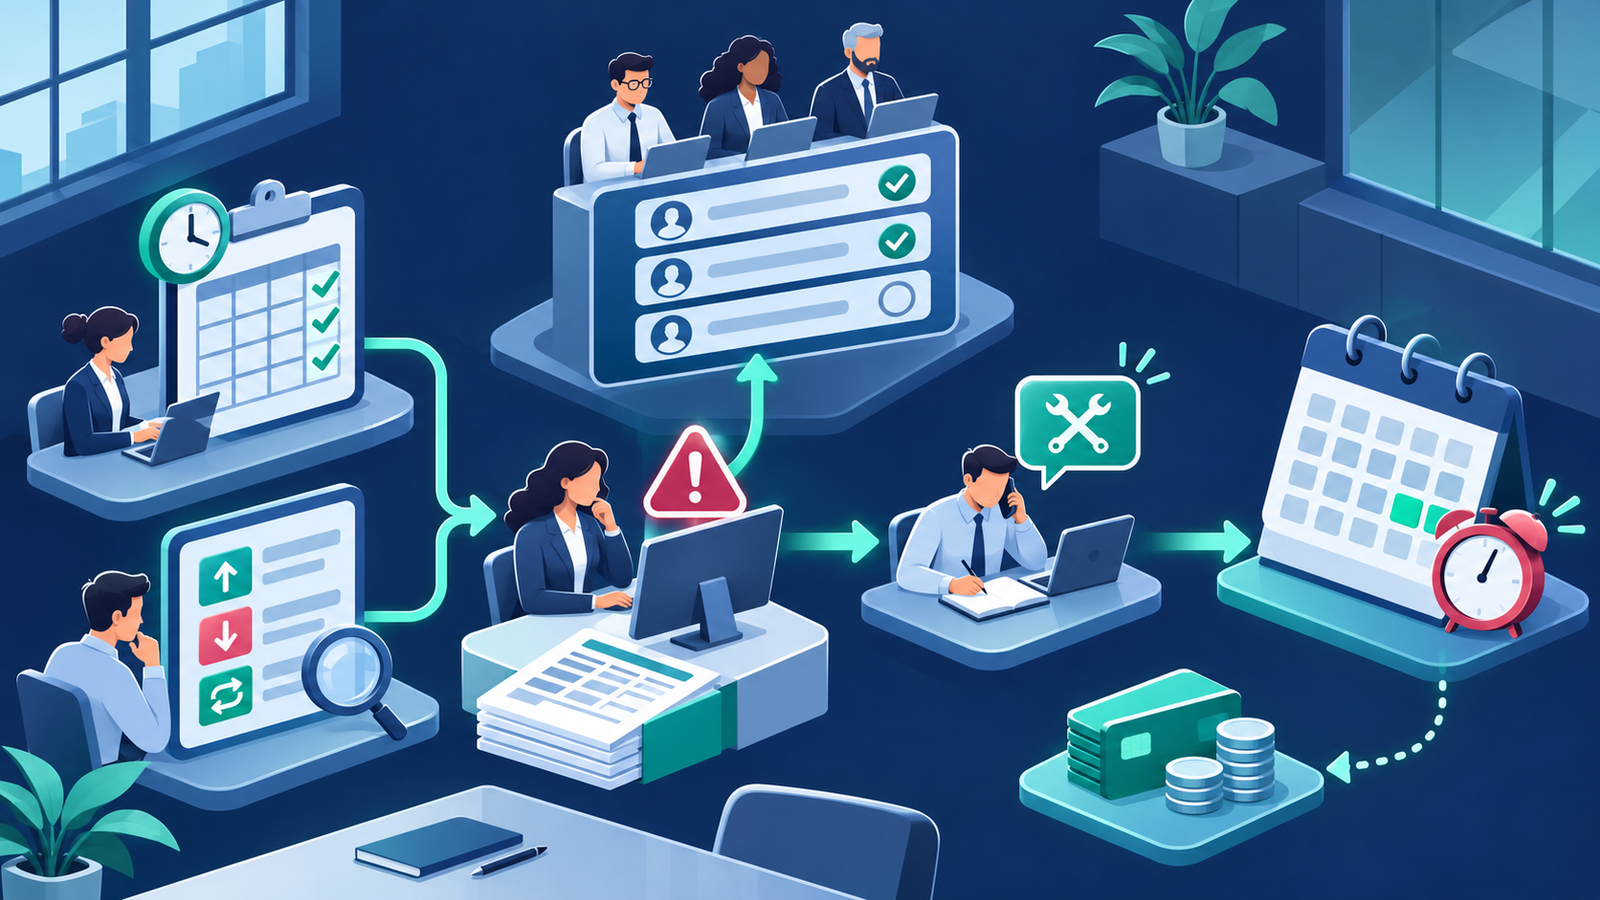
Direct answer: Payroll exceptions should be logged, risk-rated and sent to an authorised owner with the evidence needed, correction deadline and effect on payment. The employer should decide whether to correct before release, use an authorised off-cycle process or escalate further under current employment and reporting obligations.
This general guide is for Australian small-business owners, including Epping, Melbourne and Victoria. Confirm current rules and software settings for your circumstances.
Which exceptions need immediate attention?
Examples include missing hours, an unexpected pay variance, unverified bank-detail change, termination, rejected file, duplicate employee or incorrect classification input. Prioritise possible underpayment, privacy, fraud and payment-release risks.
What should the exception log record?
Capture the employee or batch reference without unnecessary exposure, issue, source, amount or possible effect, evidence, owner, deadline, decision and closure proof. Restrict sensitive payroll information to authorised people.
Who should approve a correction?
Use the employer’s delegated authority for timesheets, rates, leave, bank changes and payment release. The preparer should not silently decide a disputed employment fact.
What happens if the deadline is missed?
Escalate before payment release. Record whether the run pauses, an unaffected portion proceeds, or an authorised correction process applies. Check current Fair Work and ATO requirements rather than relying on a standing assumption.
How should the final check be documented?
Compare the corrected preview with approved inputs, save the approval, release evidence, pay slips and any STP correction. Close the exception only when the affected records agree.
What belongs in the practical checklist?
- Exception logged once
- Risk and possible pay effect assessed
- Evidence requested securely
- Authorised owner assigned
- Correction deadline before release
- Decision and approval recorded
- Payment and STP effect checked
- Closure evidence retained
What could this look like in practice?
Hypothetical example: A hypothetical Epping café finds one employee’s hours are lower than the approved roster. Payroll pauses that employee’s result, asks the authorised manager for evidence, updates the preview and records approval before release. This invented example is not employment advice or a client result.
What do business owners ask?
Should every exception stop the whole pay run?
Not necessarily. Use the documented risk, affected employees and legal obligations to decide and record the reason.
Can payroll change bank details from an email alone?
Use the employer’s secure verification process before changing sensitive payment information.
What if an error is found after payday?
Check current Fair Work and ATO requirements, correct records promptly and document the action.
Where can you continue?
Read the live parent guide, review service information, use the related payroll cut-off timetable guide, and explore the TNS Accounting homepage.
Which official sources were checked?
- Fair Work Ombudsman: record keeping and pay slips
- Fair Work Ombudsman: pay slips
- ATO: correcting information through STP
Published by TNS Accounting. Official sources checked 21 November 2026. Rules, guidance and software features can change; confirm the linked sources before acting.






