Direct answer: An overdue BAS catch-up scope should list every period covered, the records to be supplied, reconciliation and review work, technical questions, who authorises and lodges, deliverables, exclusions, fees, timing and evidence of submission. Payment of any tax debt should be treated as a separate issue from preparing and lodging accurate statements.
This is general Australian information for small businesses, including Epping, Melbourne and Victoria. It is not personal tax or legal advice.
How should overdue periods be identified?
Create a period register showing entity, reporting frequency, due date, current status and any ATO correspondence. Confirm the live lodgement record rather than assuming a software status proves receipt. The ATO BAS due-date guidance explains standard timing, while the actual account confirms what remains outstanding.
Which records should the client supply?
Specify bank and card statements, sales invoices, credit notes, supplier bills, receipts, payroll and withholding records, prior BAS, adjustments and relevant correspondence. Ask for a dated list of missing items. The ATO business record guidance describes common records businesses need to retain.
What preparation and review work is included?
State which accounts and periods will be reconciled, how GST and PAYG items will be reviewed, how exceptions will be queried, and whether amendments to earlier statements are outside scope. Identify judgement matters requiring a registered tax or BAS agent.
Who approves and lodges each BAS?
Name the preparer, reviewer, authorised client contact and lodger. The client should approve figures and unresolved assumptions before submission. If a practitioner is engaged, confirm registration and conditions on the Tax Practitioners Board public register.
What belongs in the engagement checklist?
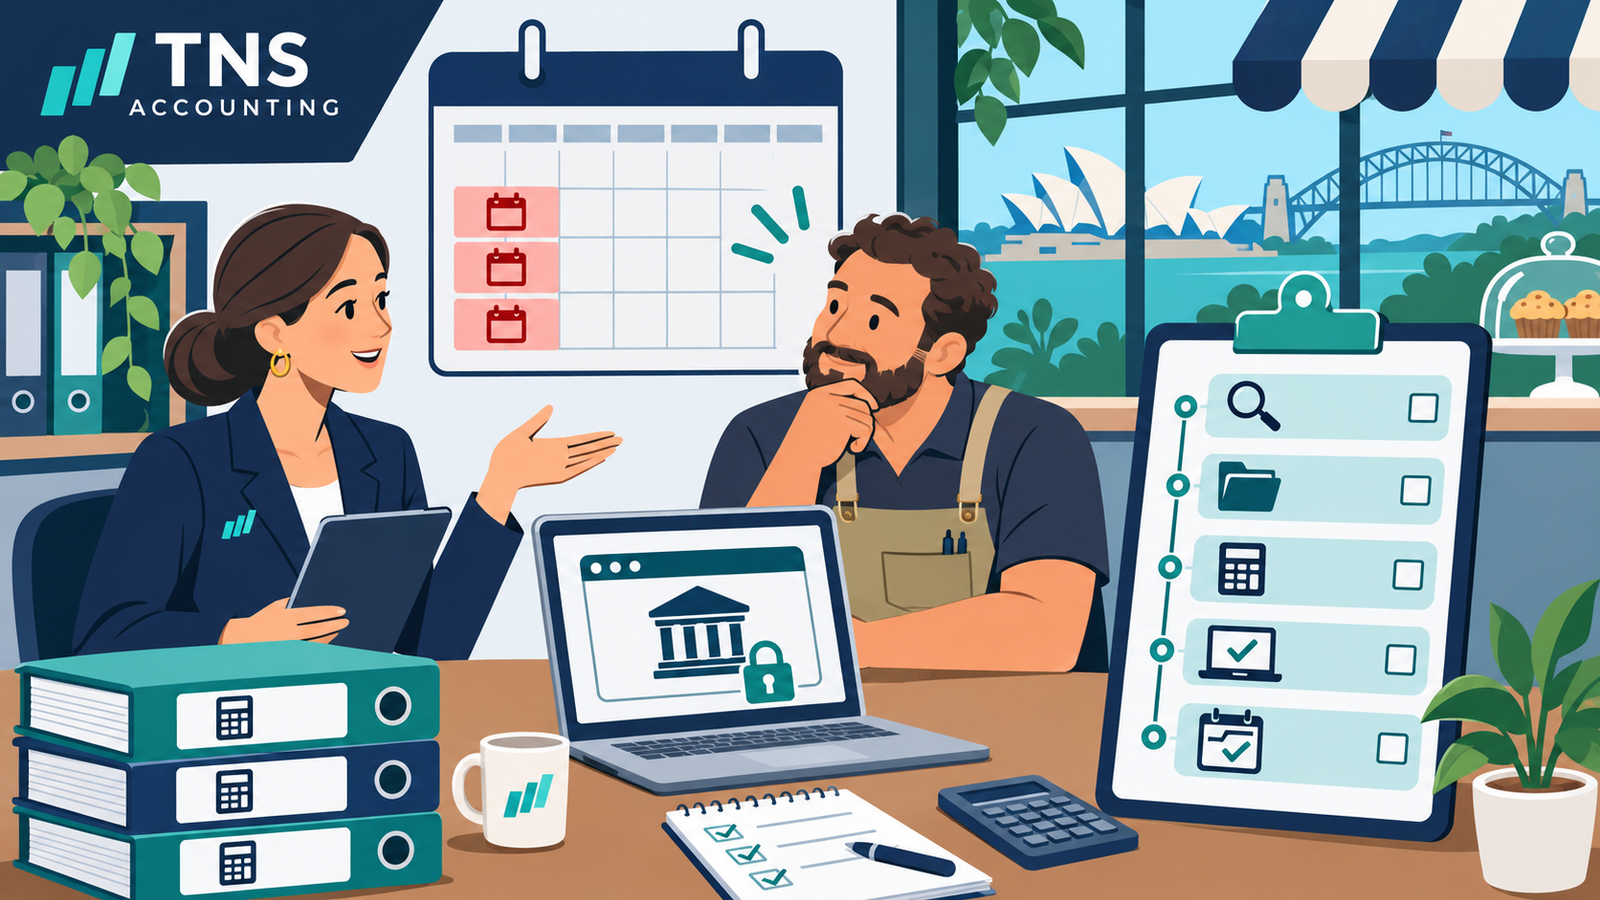
- Entity and overdue-period register
- Required documents and secure delivery method
- Reconciliation and review procedures
- Open questions and missing-evidence log
- Deliverables, exclusions and amendment boundaries
- Client approval and lodgement responsibility
- Fees, dependencies and target dates
- Lodgement receipt and follow-up responsibilities
How should payment difficulties be handled?
Keep lodgement preparation moving even if payment cannot be made in full. Record who will contact the ATO and what current information is needed. The ATO’s payment-management guidance explains available channels; eligibility and terms depend on circumstances.
What could a catch-up scope look like?
Hypothetical example: A Melbourne retailer has three overdue quarters. The written scope covers reconciliations, missing invoice queries, preparation, owner approval and lodgement receipts. A separate action assigns the owner to discuss payment options with the ATO. This example does not predict acceptance, penalties or interest.
What do owners ask about overdue BAS engagements?
Does the scope guarantee a penalty remission?
No. Do not promise ATO outcomes. Any request and decision depend on the facts and the ATO’s process.
Can incomplete records be treated as nil activity?
No. A nil BAS should only be lodged where it accurately reflects the period.
Should current bookkeeping pause during catch-up work?
No. Maintain current records so another period does not become overdue while the backlog is cleared.
Where can you continue?
Read the live overdue BAS parent guide, review BAS Tax Return Filing information, and visit the TNS Accounting homepage.
Which official sources were checked?
Published by TNS Accounting. Official sources checked 20 November 2026. Rules can change; confirm current ATO and TPB information before acting.