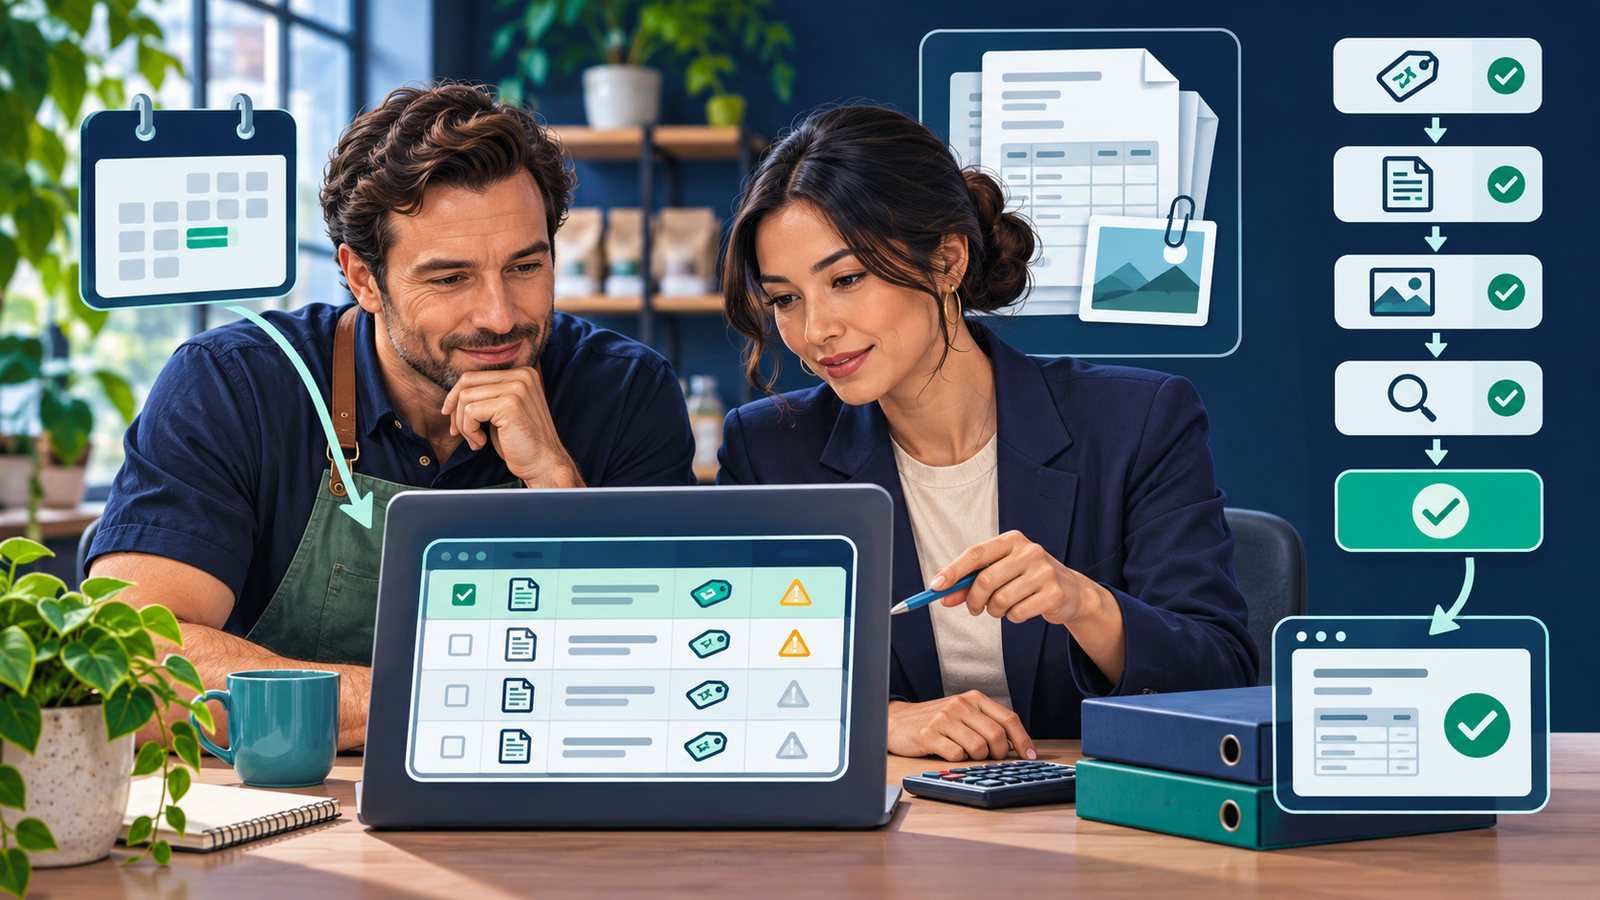
Direct answer: Validate opening balances by fixing the conversion date, exporting final source reports, comparing every account and control balance, explaining differences, and completing bank, receivables, payables, payroll and tax reconciliations before normal processing continues.
This general guide is for Australian small-business owners, including Epping, Melbourne and Victoria. Confirm current rules and software settings for your circumstances.
Which source reports should be frozen?
Save the final trial balance, balance sheet, aged receivables, aged payables, bank reconciliations, asset records, payroll and tax control reports at the agreed conversion date.
How should the conversion date be controlled?
Document the last transaction in the old system and the first in the new one. Prevent untracked entries in both systems during the cutover.
Which balances need detailed testing?
Test bank, receivables, payables, inventory, loans, fixed assets, payroll, GST and equity. A total trial balance can agree while customer or supplier details do not.
How should differences be resolved?
Record each difference, source evidence, responsible person, correction and reviewer. Do not use a balancing journal without understanding its cause.
What proves the migration is ready?
Re-run reports, reconcile control accounts, test document access and obtain owner approval. Keep the migration evidence and recovery plan.
What belongs in the practical checklist?
- Conversion date documented
- Final source reports retained
- Trial balance compared
- Subledgers matched
- Bank accounts reconciled
- Tax and payroll controls checked
- Differences explained
- Owner approval saved
What could this look like in practice?
Hypothetical example: A hypothetical Epping wholesaler migrates on month-end. The trial balance agrees, but one supplier total differs. The team fixes the opening bill detail before approving the new file. This is invented, not a migration guarantee.
What do business owners ask?
Is an agreeing trial balance enough?
No. Subledgers and control accounts also need to agree.
Can a balancing journal close every difference?
It may hide the cause. Investigate and retain evidence before correcting.
Should the old system be deleted after migration?
Retain records and access as required, with a documented archive and recovery plan.
Where can you continue?
Read the live parent guide, review service information, use the related data cleanup before migration guide, and explore the TNS Accounting homepage.
Which official sources were checked?
Published by TNS Accounting. Official sources checked 22 November 2026. Rules, guidance and software features can change; confirm the linked sources before acting.