

Direct answer: A close service scope should name the entities, accounts, periods and cut-off; the reconciliations and journals included; the source records required; who prepares and approves each step; the reports delivered; how exceptions are handled; and the target completion date. It should also distinguish recurring month-end work from year-end adjustments.
This guide is general information for Australian small-business owners, including Epping, Melbourne and Victoria. The scope should match the business, reporting purpose and adviser responsibilities.
Which accounts and cut-offs should the scope cover?
List every bank, card, payment platform, receivable, payable, payroll, tax, loan and relevant asset or liability account. Define the period end, document cut-off and treatment of late invoices or transactions. A scope that says only “reconcile the books” leaves important boundaries unclear.
Which close procedures should be specified?
State whether the work includes bank and card reconciliation, receivables and payables review, payroll and super liabilities, GST control accounts, loans, inventory, fixed assets, accruals, prepayments, depreciation, suspense accounts and inter-entity balances. Note which items need an appropriately registered adviser or management decision.
What records and approvals are needed?
The owner should provide complete bank statements, invoices, bills, payroll reports, loan statements, asset records and explanations for exceptions by an agreed date. Identify who can approve write-offs, journals, estimates and historical changes. The Australian Government’s record-keeping guidance explains why financial and transaction evidence must be retained.
What belongs in the scope checklist?
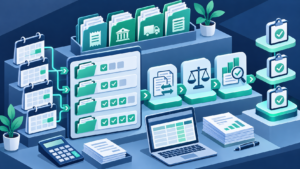
- Entities, period, accounts and reporting basis.
- Document cut-off and treatment of late items.
- Reconciliations and control accounts included.
- Recurring journals, estimates and supporting evidence.
- Owner queries, response deadlines and escalation.
- Preparer, reviewer and approval responsibilities.
- Reports, comparison periods and delivery date.
- Year-end tasks that sit outside the monthly scope.
- Exception log and unresolved-item treatment.
- Retention of workpapers and final sign-off.
What could a clear close scope look like?
Hypothetical example: A Melbourne wholesaler agrees that month-end covers all bank and card accounts, receivables, payables, payroll liabilities and GST controls by the tenth business day. Inventory valuation and tax adjustments are separately assigned for year end. Late documents go to an exception log for owner approval. This is an illustrative workflow, not a client result.
How should the reporting output be defined?
Name the reports, comparison period, level of detail and questions they must answer. Specify whether delivery includes a profit and loss statement, balance sheet, cash-flow view, aged receivables, aged payables and a list of unresolved items. The government defines bank reconciliation as checking the cash book against bank statements; a software “reconciled” flag should not replace that evidence.
Where does this fit in the wider process?
Use the live month-end reconciliation and financial close pillar, review accruals and prepayments, read Bookkeeping and Financial Reporting information, or visit the homepage.
Frequently asked questions
Is month-end close the same as year-end close?
No. Month-end usually focuses on recurring reconciliations and management reporting. Year end can add tax, statutory, inventory, asset and adviser adjustments.
Who should approve close adjustments?
The scope should assign approval according to the adjustment’s nature and risk. Material or tax-related items may need management and registered adviser review.
What happens when documents arrive late?
Record them in an exception process. The scope should define whether the period remains open, an estimate is approved or the item is handled in the next period.
Which official sources were checked?
- Australian Government: Record keeping
- Australian Government: Key financial terms
- Australian Government: Set up a cash flow statement
Published by TNS Accounting. Official sources checked 20 November 2026. Define responsibilities and obtain advice appropriate to the business and reporting purpose.



One Response