

Direct answer: Keep source documents, reconciled balances, lodged versions and explanations for material transactions in a traceable evidence pack. Confirm the actual review scope and requested periods. Organised records make questions easier to answer, but they do not guarantee an audit outcome.
General information for Australian small-business owners, including Epping, Melbourne and Victoria. Treatment depends on current rules, records and individual circumstances.
What should be confirmed when a request arrives?
Verify the contact through official channels and record the entity, periods, issues, information requested and response date. Identify the person coordinating the response and obtain registered tax or legal advice where appropriate. A general readiness checklist does not override the specific request.
How should the evidence pack be organised?
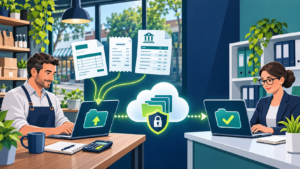
Index records by account, transaction or issue, with dates and clear filenames. Keep bank statements, invoices, contracts, payroll and super records, asset schedules and calculations as relevant. Link each material ledger figure to the supporting document and preserve the original record.
Which reconciliations should be ready?
Support bank, card, debtor, creditor, payroll, GST, loan and other significant balances with dated schedules. Explain reconciling items and unusual journals. Retain the version used for lodged BAS or returns so later bookkeeping changes can be distinguished from what was actually reported.
What belongs in the review-readiness checklist?
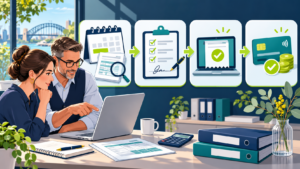
- Confirm the request, entity, period and deadline.
- Save the original lodged and reported versions.
- Index source documents and calculations.
- Reconcile material accounts to independent evidence.
- Document corrections, assumptions and approvals.
- Assign unresolved questions to a responsible person.
- Use secure delivery and record what was supplied.
- Retain advice, correspondence and the final outcome.
How should missing records or errors be handled?
Keep an honest exception list and explain efforts to obtain missing evidence. Do not recreate documents as if they were originals or silently alter history. Ask the appropriate adviser about amendments or voluntary disclosure if a lodged statement is affected, and preserve the correction trail.
What could this look like in practice?
Hypothetical example: A Melbourne company is asked about selected expense claims. It provides an indexed ledger extract, invoices, business-purpose notes and reconciliation. One missing invoice remains on an exception list while the adviser considers its effect. The scenario promises no audit result.
Where does this fit in the wider process?
Use the live parent guide, review our service information, or visit the TNS Accounting homepage. Read the related bookkeeping clean-up control guide for the next step.
Frequently asked questions
Does a clean set of financial reports prove every claim?
No. The underlying evidence and calculations must support the reported amounts.
Should originals be replaced with tidier versions?
Preserve originals and clearly label working copies, explanations and corrections.
Is preparing records the same as providing an audit service?
No. Record preparation and an independent audit or assurance engagement are different services with different scope and requirements.
Which official sources were checked?
Published by TNS Accounting. Updated and official sources checked 20 November 2026. Rules and software features can change; check the linked sources before acting.
For the wider routine, review our Bookkeeping service information and bookkeeping clean-up guide.




2 Responses