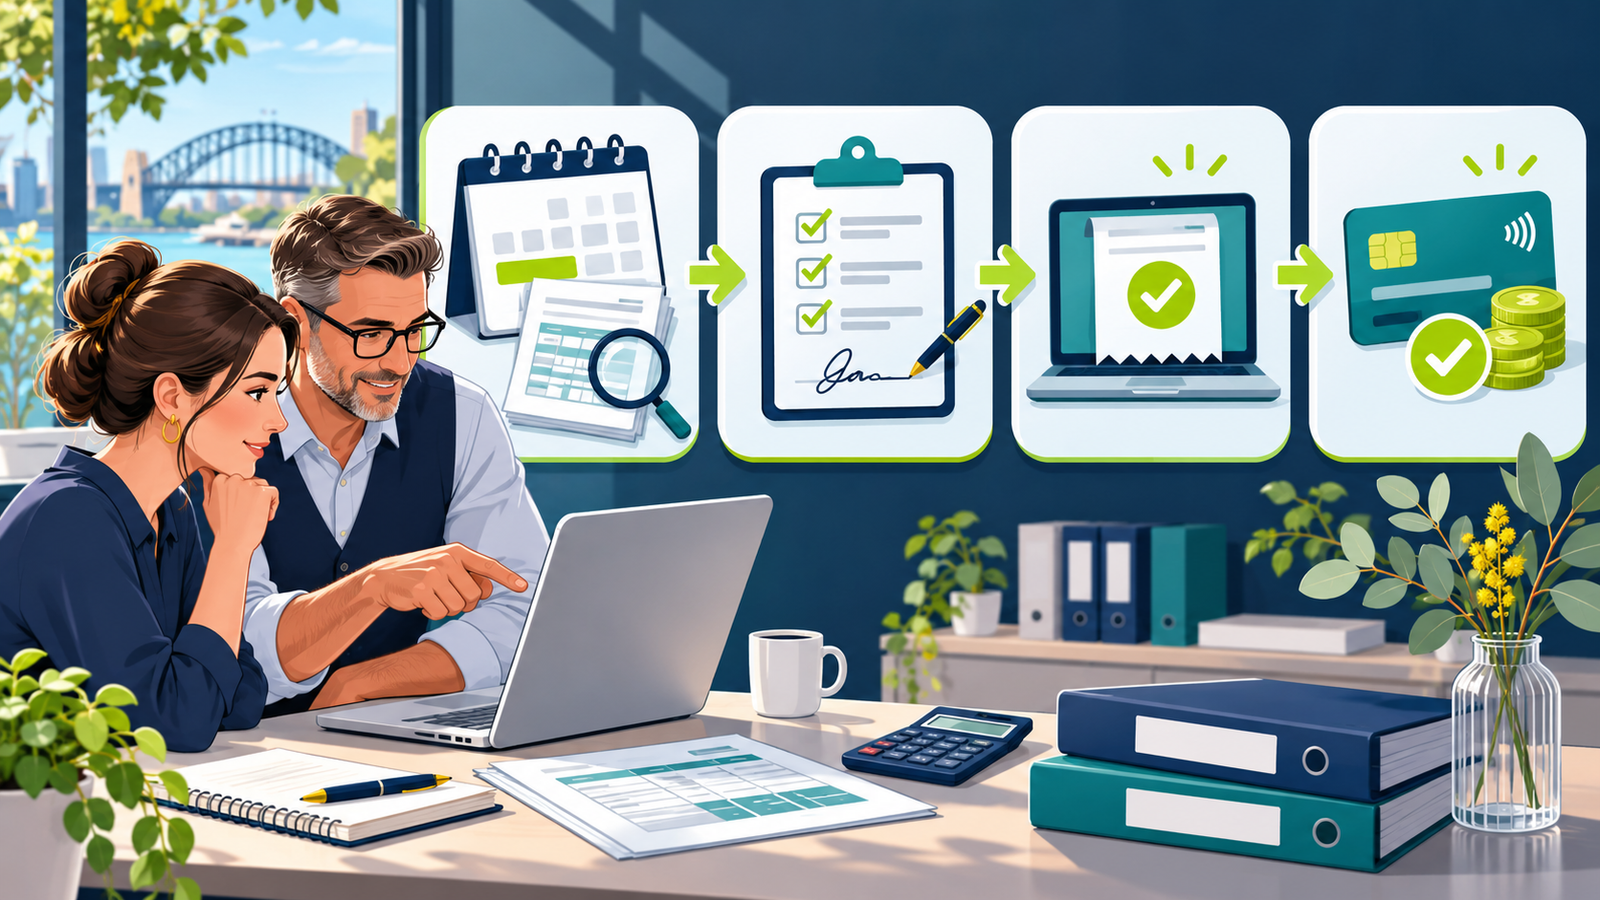
Direct answer: Changes during overdue BAS catch-up work should be prepared from reconciled evidence, reviewed by a person competent to assess the GST or PAYG treatment, approved by the business owner for the figures and known gaps, and lodged only by the business or an appropriately authorised registered practitioner. Lodgement approval and a payment arrangement are separate decisions.
This general guide is for Australian small-business owners, including Epping, Melbourne and Victoria. Confirm current rules and product settings for your circumstances.
Which changes need explicit approval?
Record approval for changed sales or purchase figures, GST coding, payroll withholding, prior-period adjustments, estimated items, nil reporting and the decision to lodge an incomplete period. Never use a nil amount merely to clear an overdue label.
Who should review the technical treatment?
A reviewer should trace material amounts to source records, reconcile bank and payroll totals and identify items needing tax or BAS advice. If a practitioner is relied upon, confirm current registration and scope through the Tax Practitioners Board public register.
What should the owner confirm before lodgement?
The owner should receive a period summary, figures, unresolved items and effect on the account. Approval should record the version and date. Community discussions repeatedly show concern when owners cannot see whether a BAS was lodged; keep the official receipt rather than relying on reassurance.
Who may lodge the BAS?
The business may lodge through its authorised channel, or an authorised registered tax or BAS agent may lodge within their permitted services. Keep the submission reference and verify the lodged status in the relevant ATO account.
How should payment decisions be controlled?
Record the amount due, due date, payment owner and any current arrangement. Lodging does not by itself establish a payment plan. Use current ATO information and keep the agreed terms and payment evidence.
What belongs in the practical checklist?
- Entity, period and due date confirmed
- Reconciled source records and adjustment log
- Technical reviewer and registration checked
- Owner approval tied to final figures
- Authorised lodger identified
- ATO receipt and account status retained
- Payment action or arrangement recorded
- Next current-period deadline protected
What could this look like in practice?
Hypothetical example: A hypothetical Victorian trades business has three overdue quarters. The bookkeeper prepares a period register, a registered practitioner reviews GST adjustments, and the owner approves each final statement. Receipts and payment actions are saved separately. No ATO outcome is assumed.
What do business owners ask?
Can the preparer approve their own material adjustment?
A separate competent review is preferable for material or uncertain changes, especially before overdue statements are lodged.
Does owner approval make an incorrect BAS acceptable?
No. Approval records the decision and evidence; the reported information still needs to be accurate.
Can a payment plan be assumed after lodging?
No. Confirm any arrangement through current ATO channels and retain the agreed terms.
Where can you continue?
Read the live parent guide, review service information, and explore the TNS Accounting homepage.
Which official sources were checked?
Published by TNS Accounting. Official sources checked 20 November 2026. Rules, guidance and software features can change; confirm the linked sources before acting.