
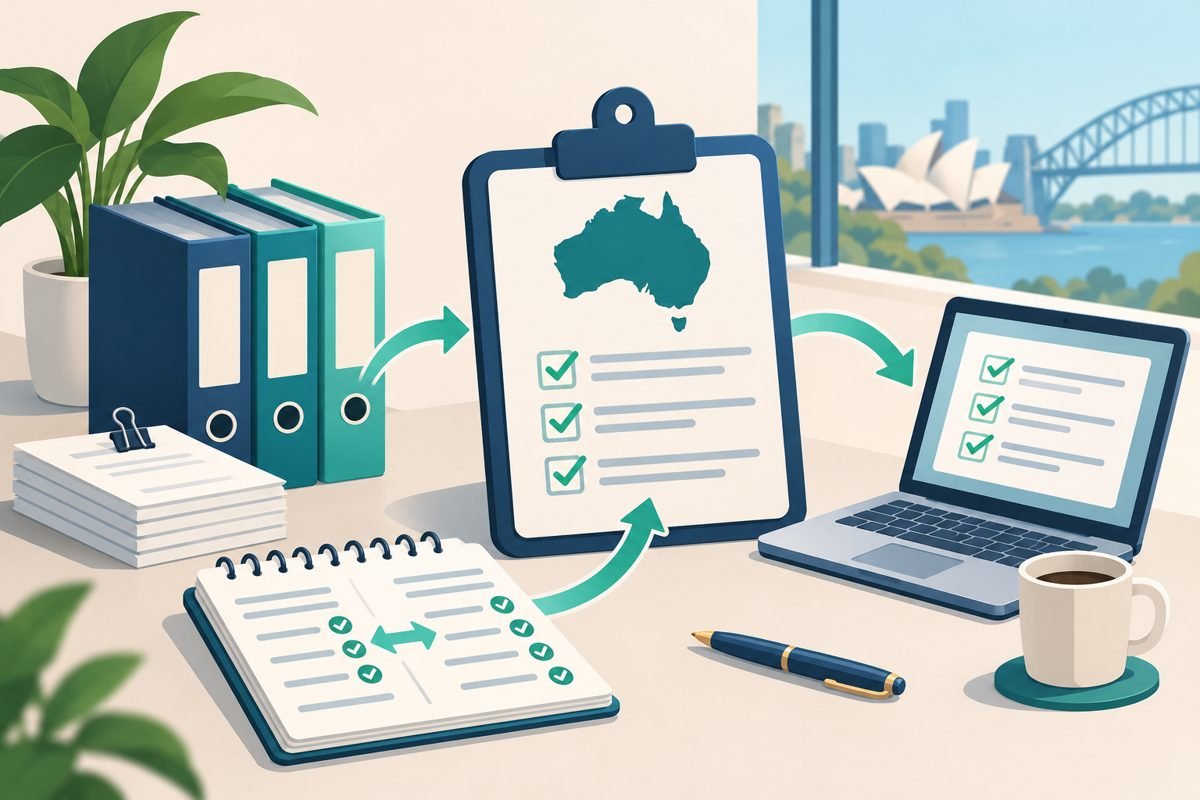
Direct answer: Prepare reconciled financial statements, ledgers, bank and loan records, asset schedules, payroll and super records, tax reconciliations and evidence for material transactions.
Why does this matter for a small business?
The company return depends on reliable books and adjustments that can be traced to records; unresolved balances should not be hidden in year-end journals. The process should fit the business’s actual volume and responsibilities rather than rely on software defaults or memory.
What practical process should you follow?
- Complete bank and balance-sheet reconciliations
- Review revenue, expenses and private or related-party transactions
- Update fixed assets, loans, payroll and tax control accounts
- Document adjustments, approvals and records supplied to the tax practitioner
What does this look like in practice?
Hypothetical example: A Melbourne company finds director-paid expenses mixed with company costs. The items are documented and reviewed before the final accounts and tax return are approved.
What should you check before signing off?
- Source records are complete for the period.
- Material balances agree to independent evidence.
- Exceptions have an owner, due date and written resolution.
- The final reviewer understands large movements and judgements.
- Required records and approvals are stored securely.
For related guidance, see the live parent guide, the General Accounting service page and TNS Accounting homepage.
Frequently asked questions
Is a company return the same as an owner’s return?
No. A company is a separate taxpayer, although company transactions may affect owners or directors.
Should old suspense balances be cleared?
Investigate them with evidence. Do not force balances to zero merely to finish the return.
Who can provide paid company tax services?
Generally, paid tax agent services must be provided by an appropriately registered practitioner.
Which sources were checked?
Published by TNS Accounting. Sources checked 14 November 2026. General information only; confirm obligations for your circumstances with the relevant authority or an appropriately registered practitioner.




One Response