
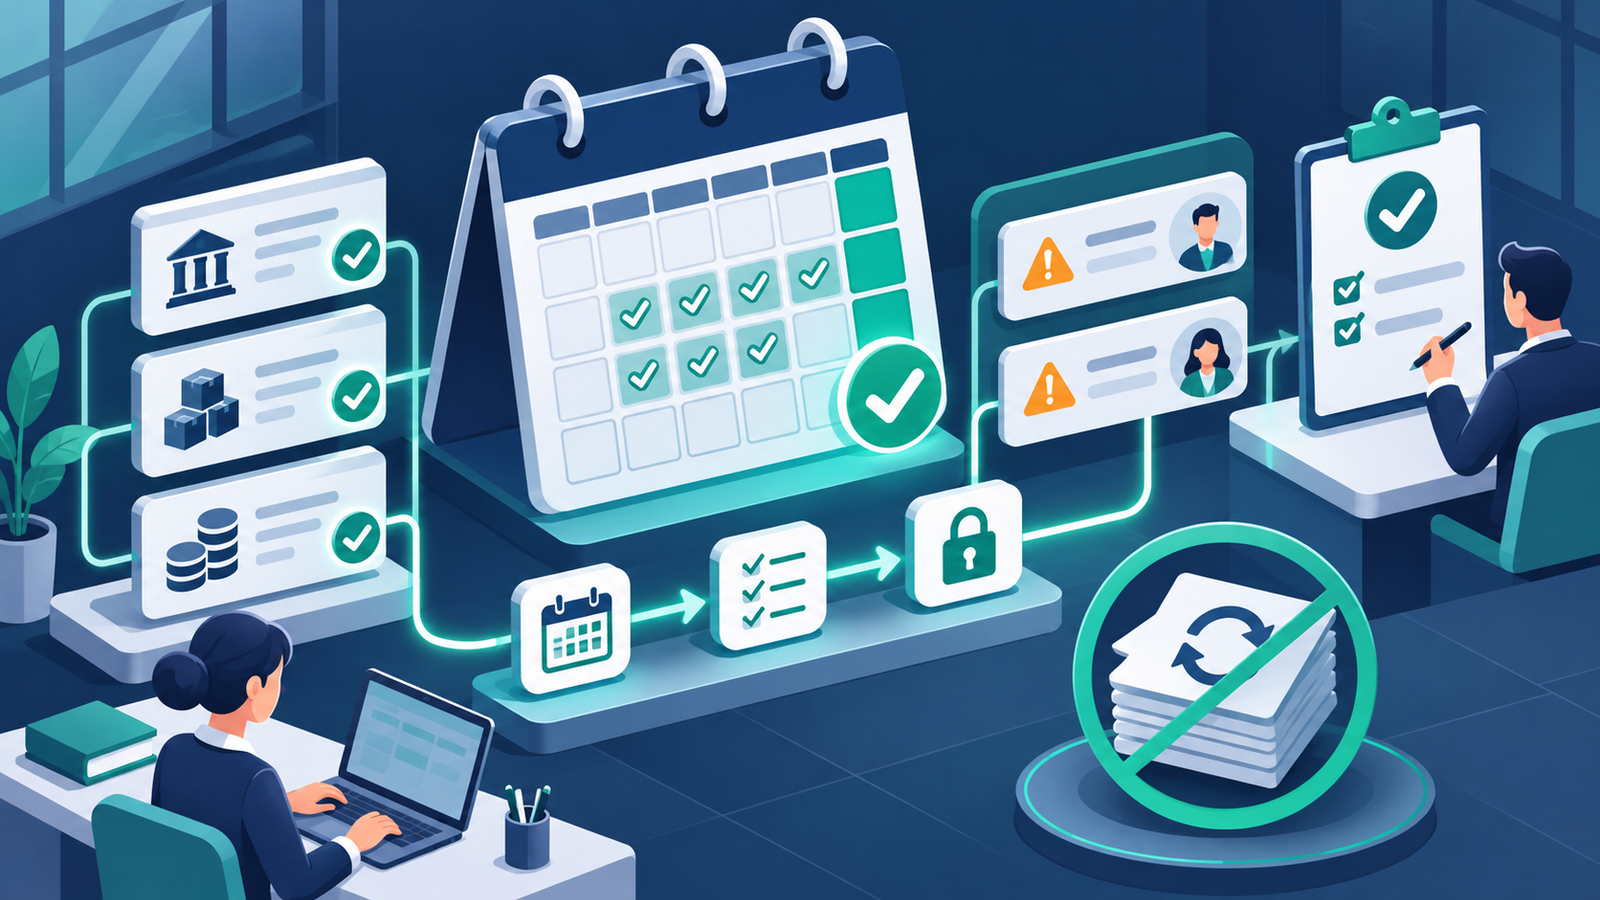
Direct answer: A close calendar prevents reconciliation rework when it sequences dependencies, names evidence cut-offs, assigns each balance and reviewer, defines exception rules, protects approved versions and records final sign-off. A list of due dates alone is not enough if people can complete work before upstream records are ready.
This general guide is for Australian small-business owners, including Epping, Melbourne and Victoria. Confirm current rules and software settings for your circumstances.
Which dependencies belong on the calendar?
Map bank statements, sales cut-off, supplier bills, payroll, inventory, loans, tax controls and inter-entity balances before the reports that depend on them. Mark tasks that cannot start until another control is complete.
How should reconciliation ownership be divided?
Give each account a preparer, reviewer, evidence standard and due date. Where staffing allows, separate preparation from approval. If one person performs both, add an explicit owner review of unusual or material items.
What should the exception rule contain?
Record the amount, affected account, evidence missing, possible reporting effect, owner and resolution date. State when a report remains provisional and when an issue blocks sign-off.
How does version control reduce repeated work?
Use one approved report pack, date it and link it to the reconciliations and journals reviewed. After sign-off, record any reopened period, changed entry and reports requiring reissue.
What should the final review confirm?
Confirm reconciliations, material journals, unusual movements, open exceptions, approval and secure storage. The Australian Government recommends reviewing core financial statements and investigating unusual changes.
What belongs in the practical checklist?
- Upstream dependencies mapped
- Evidence cut-offs agreed
- Preparer and reviewer assigned
- Reconciliation standard defined
- Exception and provisional-report rules
- Approved version identified
- Reopened-period changes tracked
- Final sign-off and archive completed
What could this look like in practice?
Hypothetical example: A hypothetical Victorian agency repeatedly redoes receivables because late sales credits arrive after review. Its close calendar moves the sales cut-off before reconciliation and requires one exception log before sign-off. This invented example is not a client result.
What do business owners ask?
Should every account close on the same day?
No. Sequence tasks around dependencies and reporting risk rather than using one arbitrary deadline.
Can a materiality rule remove the need to record exceptions?
No. It may guide treatment, but known issues and their possible effect should still be documented.
Who can reopen a signed-off period?
Restrict access, require a reason and recheck affected reconciliations and reports.
Where can you continue?
Read the live parent guide, review service information, use the related monthly financial reporting controls guide, and explore the TNS Accounting homepage.
Which official sources were checked?
- ATO: banking records
- ATO: timing record-keeping tasks
- Australian Government: review financial health
Published by TNS Accounting. Official sources checked 21 November 2026. Rules, guidance and software features can change; confirm the linked sources before acting.






