
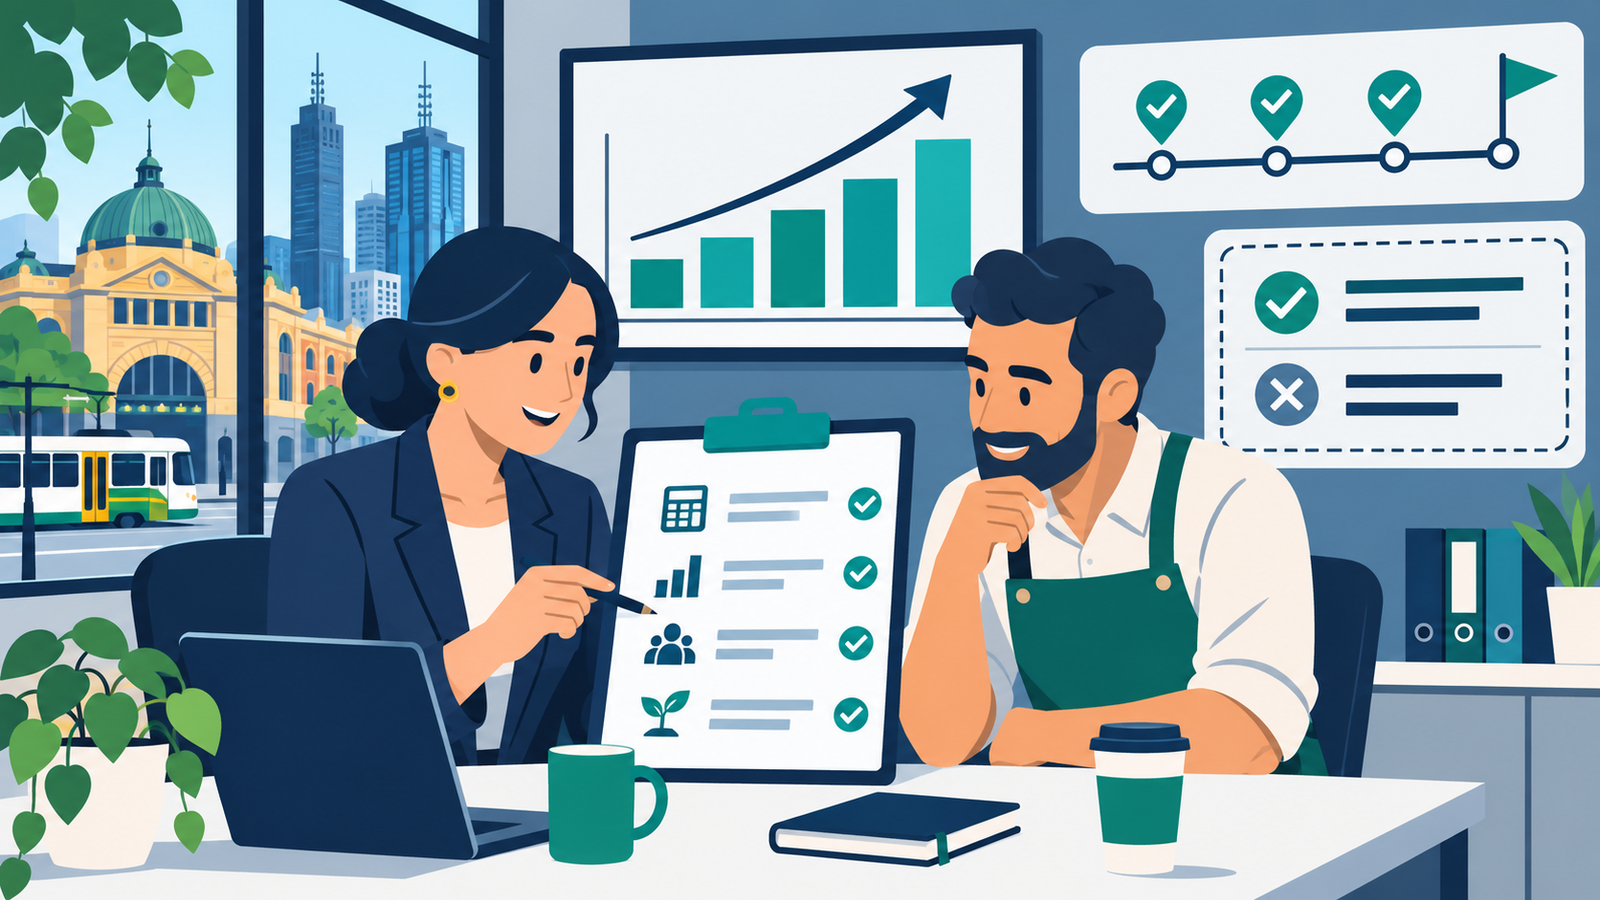
Direct answer: A useful business advisory services scope should identify the decisions to support, the financial information needed, specific deliverables, responsibilities, meeting rhythm, exclusions and review dates. It should describe work that can be checked—not promise growth or a particular result.
What problem should the advisory work solve?
Begin with the owner’s decision: improving cash resilience, testing capacity for growth, setting a budget, comparing options or building a reporting rhythm. A broad request to “help us grow” is too vague to price, deliver or review.
For an Epping or Melbourne small business, local operating conditions may affect assumptions, but the scope should still separate facts, forecasts and owner choices. The Australian Government guide to growing a business recommends understanding current performance, setting measurable goals and identifying the actions, people and resources required.
Which deliverables make the scope clear?
- A starting financial health check and agreed baseline
- A budget, cash-flow forecast or scenario model with documented assumptions
- A short action register showing owner, adviser and due date
- A dashboard or management report with agreed definitions
- Scheduled decision meetings and written follow-up notes
The deliverables should match the problem. A forecast may support a hiring decision; it does not guarantee the sales, margins or timing assumed. Link the advisory work to the broader business growth financial checks that will be kept current.
How should responsibilities and information deadlines be divided?
State who supplies bank, sales, payroll, debt and pipeline information; who checks completeness; who approves assumptions; and who acts on recommendations. Late or incomplete inputs should trigger a revised timetable rather than silent guesswork.
Owners should retain decision authority. The adviser can analyse information and explain trade-offs, while legal, finance, investment, tax or employment matters may require an appropriately authorised specialist.
What should be excluded from the engagement?
Record exclusions explicitly: bookkeeping corrections, tax return preparation, legal advice, finance broking, valuation, investment advice, implementation or unlimited on-call support unless included. Clear exclusions prevent an advisory conversation from being mistaken for a separate regulated or operational service.
If bookkeeping or accounts are unreliable, the scope should pause or add a data-cleanup stage. The General Accounting service page explains the broader accounting context.
How should success be measured without making promises?
Use process and decision measures such as forecast completion, variance explanations, debtor days reviewed, cash buffer policy agreed, actions completed and management reports delivered on time. Commercial outcomes should be monitored, but not represented as guaranteed client results.
Agree a baseline, reporting period and data source. A metric without a definition invites disputes—for example, clarify whether margin means gross margin from the accounting system or a manually adjusted management measure.
When should the scope be reviewed?
Review it after the first information check, at an agreed quarterly or milestone date, and whenever the business model, ownership, funding, staffing or software changes. Close completed work, document new questions and obtain approval before adding material tasks.
Small-business owners can use the TNS Accounting homepage to navigate related accounting resources rather than treating one advisory scope as an unlimited service.
Practical checklist
- Write the decision or problem in one sentence
- List deliverables and the data each requires
- Name the owner and adviser responsibilities
- Set meeting, reporting and approval dates
- Define metrics, assumptions and data sources
- List exclusions and referral needs
- Explain variation and cancellation arrangements
- Schedule a written scope review
Hypothetical example
Hypothetical example only: A Melbourne wholesaler is considering a second warehouse. Its scope includes a 13-week cash-flow model, two volume scenarios, a monthly variance meeting and an action register. The owner supplies signed lease terms and sales forecasts; the adviser documents assumptions. Loan advice, legal review and lease negotiation are excluded and referred separately.
Frequently asked questions
Can an advisory scope change after work starts?
Yes. Record the requested change, effect on timing and fees, revised deliverables and approval before extra work begins.
Should business growth be guaranteed?
No. A sound engagement can improve information and decision discipline, but customers, costs, finance and execution remain uncertain.
How often should advisory meetings occur?
Use the shortest rhythm that supports the decision—often monthly during active planning and less often once actions are stable.
Sources checked
- Australian Government – Guide to growing your business
- Australian Government – Get help for your business
- Australian Government – Adviser finder
Published by TNS Accounting. Source check completed 20 November 2026. This general information does not replace advice for your circumstances.



One Response