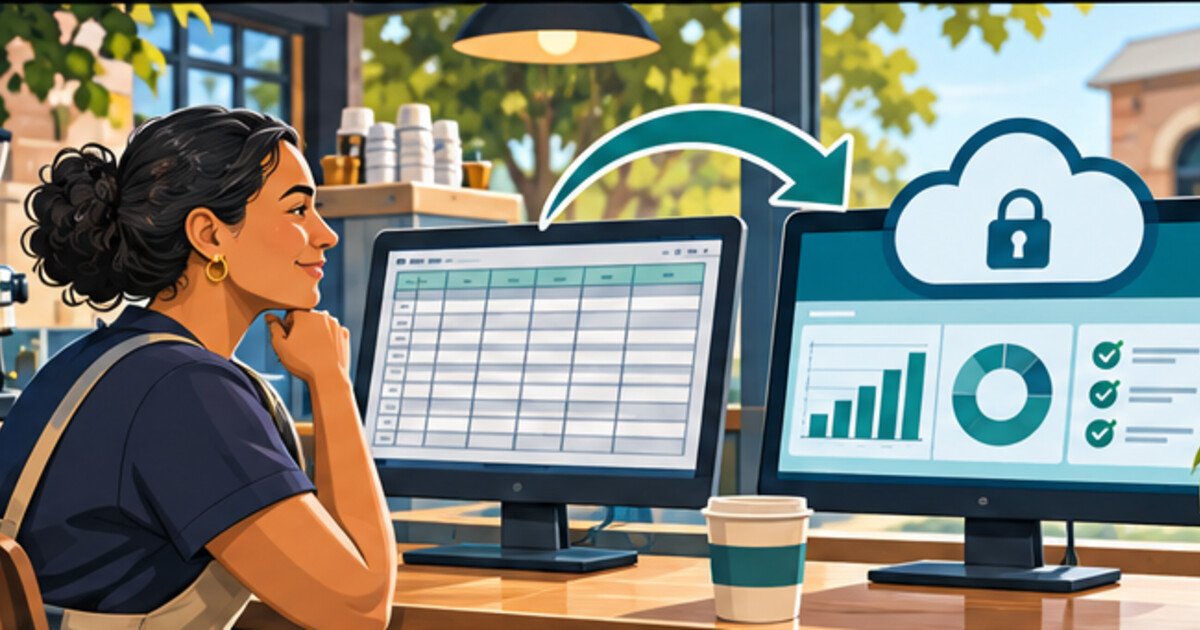
Direct answer: Move when transaction volume, GST, payroll, multiple users or reconciliation complexity makes the spreadsheet hard to control. The migration should preserve source evidence, opening balances and an audit trail rather than merely copy totals.
This guide gives general information for Australian small-business owners, with practical context for Epping, Melbourne and Victoria. It is not personal tax, legal, lending or employment advice.
What is the practical starting point?
Move when transaction volume, GST, payroll, multiple users or reconciliation complexity makes the spreadsheet hard to control. The migration should preserve source evidence, opening balances and an audit trail rather than merely copy totals.
Which records should be prepared?
Archive the final spreadsheet, bank statements, invoices, bills, payroll and BAS records; define a cut-off date; map accounts and tax codes; and document opening debtors, creditors, assets, loans and equity.
Which checks reduce errors?
Remove duplicates, test formulas, reconcile the last spreadsheet period, import in a sandbox where possible, compare opening trial balances and keep the old records read-only for retention.
What should the owner put on the checklist?
- Confirm the legal entity, period and responsible decision-maker
- Collect complete source records and independent statements
- Document assumptions, classifications and current settings
- Reconcile control totals and investigate every material exception
- Keep approvals, corrections and final evidence securely
- Set the next review, payment or lodgment date
How might this work in practice?
Hypothetical example: A hypothetical Melbourne consultant reaches GST registration and adds staff. They close and reconcile the spreadsheet at month-end, migrate supported balances, then compare the first software reports with the signed-off workbook.
Where does this fit in the wider process?
Use the live parent guide for the wider control framework, review our Bookkeeping service information, or visit the TNS Accounting homepage.
What should be escalated?
Seek suitable registered tax, legal, employment or finance advice when the facts are uncertain, a statutory deadline applies, or a correction affects lodged forms, employee entitlements, contracts or personal liability.
Frequently asked questions
Can accounting software complete this work automatically?
Software can support capture and calculation, but the business still needs to verify records, configuration, legal context, exceptions and approval.
How often should this be reviewed?
Review it at each relevant close or pay cycle and whenever the business, law, rates, software or responsible people change.
Which official sources were checked?
Published by TNS Accounting. Official sources checked 19 November 2026. Rules, rates and software features can change; check the linked sources before acting.