
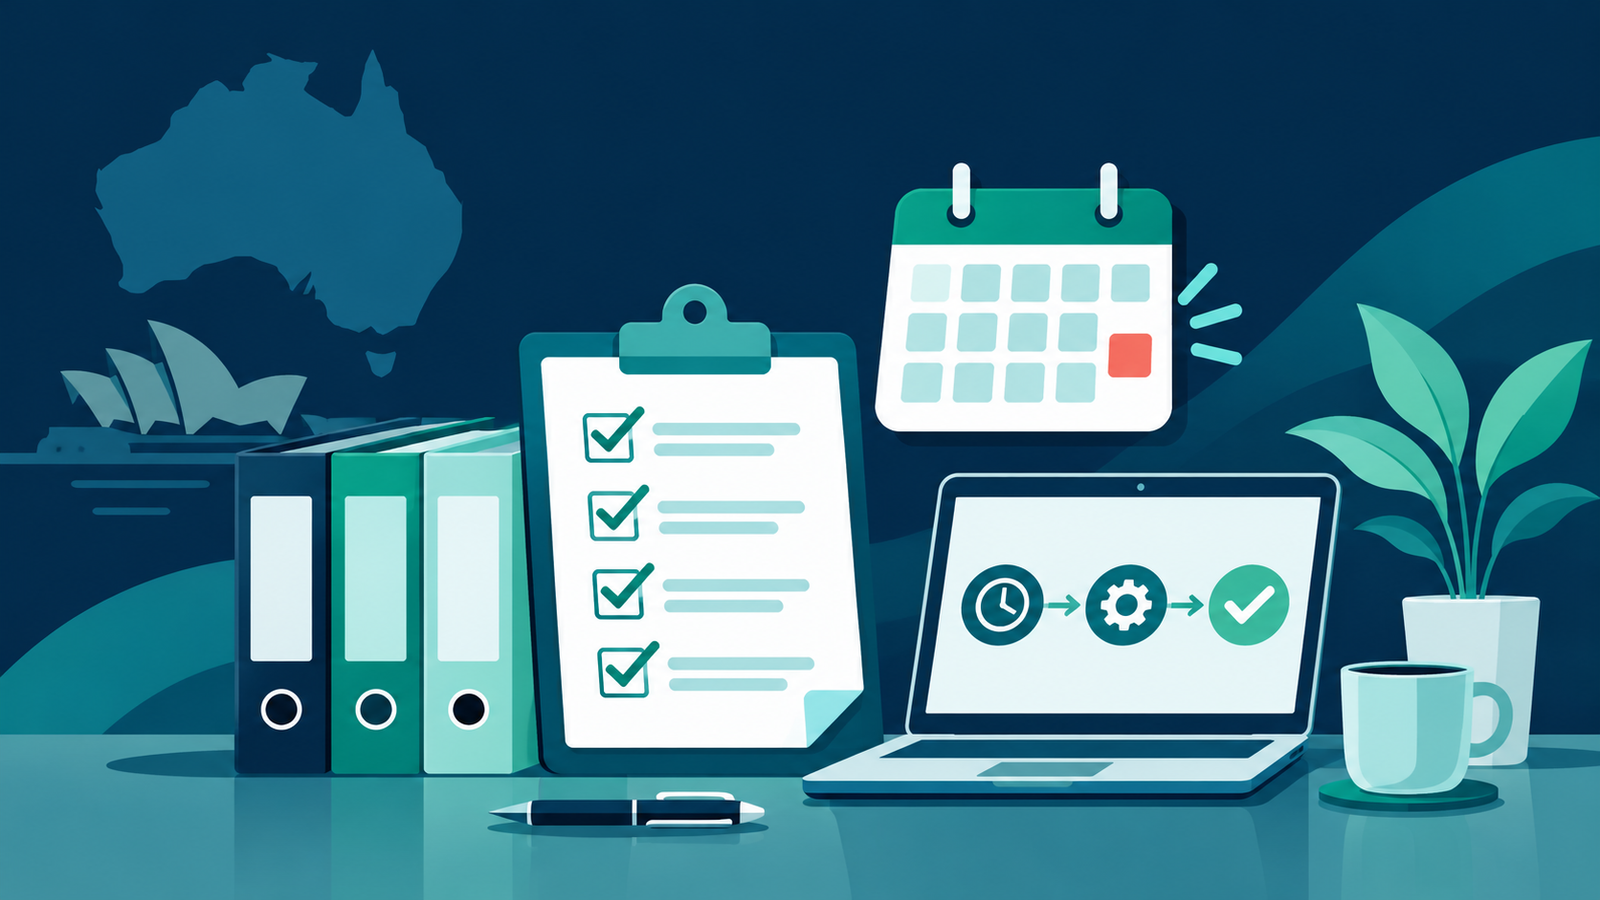
If a tax return is overdue, first confirm which years and entities still require lodgment, collect the records for each period and lodge accurate outstanding returns or non-lodgment advice as soon as possible. Do not wait for perfect records or ignore notices; document gaps and ask the ATO or a registered tax agent about the correct process.
How do you confirm what is actually overdue?
Check ATO online services, entity records and prior notices for each income year. Separate individual, sole trader, partnership, trust and company obligations because one lodged return does not clear every entity.
Which records should be rebuilt first?
Start with bank statements, sales, expenses, payroll, BAS, asset transactions and prior-year closing balances. Reconcile major totals and record assumptions or missing evidence instead of inventing figures.
What if no return was required?
A non-lodgment advice may still be required. Confirm eligibility for the particular year before submitting one, especially where an ABN, business income or other reportable activity existed.
How should payment pressure be handled?
Lodgment and payment are separate issues. Lodge accurately, quantify any debt and review current ATO payment options; interest may continue, so include future obligations in any plan.
What practical checklist should you use?
- List overdue years and entities
- Download notices and account statements
- Rebuild records from the oldest year
- Identify missing evidence and assumptions
- Lodge returns or valid non-lodgment advice
- Plan any resulting debt and current obligations
What does a simple example show?
Hypothetical example: An Epping sole trader discovers two overdue individual returns and one missing business schedule. The owner reconciles bank records year by year, lodges accurately and then reviews the resulting payment position. This is illustrative.
Frequently asked questions
Should the newest return be lodged first?
Check the ATO position and dependencies. Working from the oldest incomplete year often makes later opening balances easier to support.
Will an overdue return always attract a penalty?
Not necessarily. Penalties and interest depend on the facts; lodge promptly and rely on the ATO’s current decision.
Can missing receipts be estimated?
Do not invent deductions. Use available evidence and seek specific advice about acceptable substantiation.
Where can you continue?
Use the live parent guide, review the relevant TNS Accounting service, or visit TNS Accounting for the wider resource library.
Official sources checked
Published by TNS Accounting. Sources checked 15 November 2026. General educational information only; treatment depends on current law, software, records and individual circumstances.





One Response