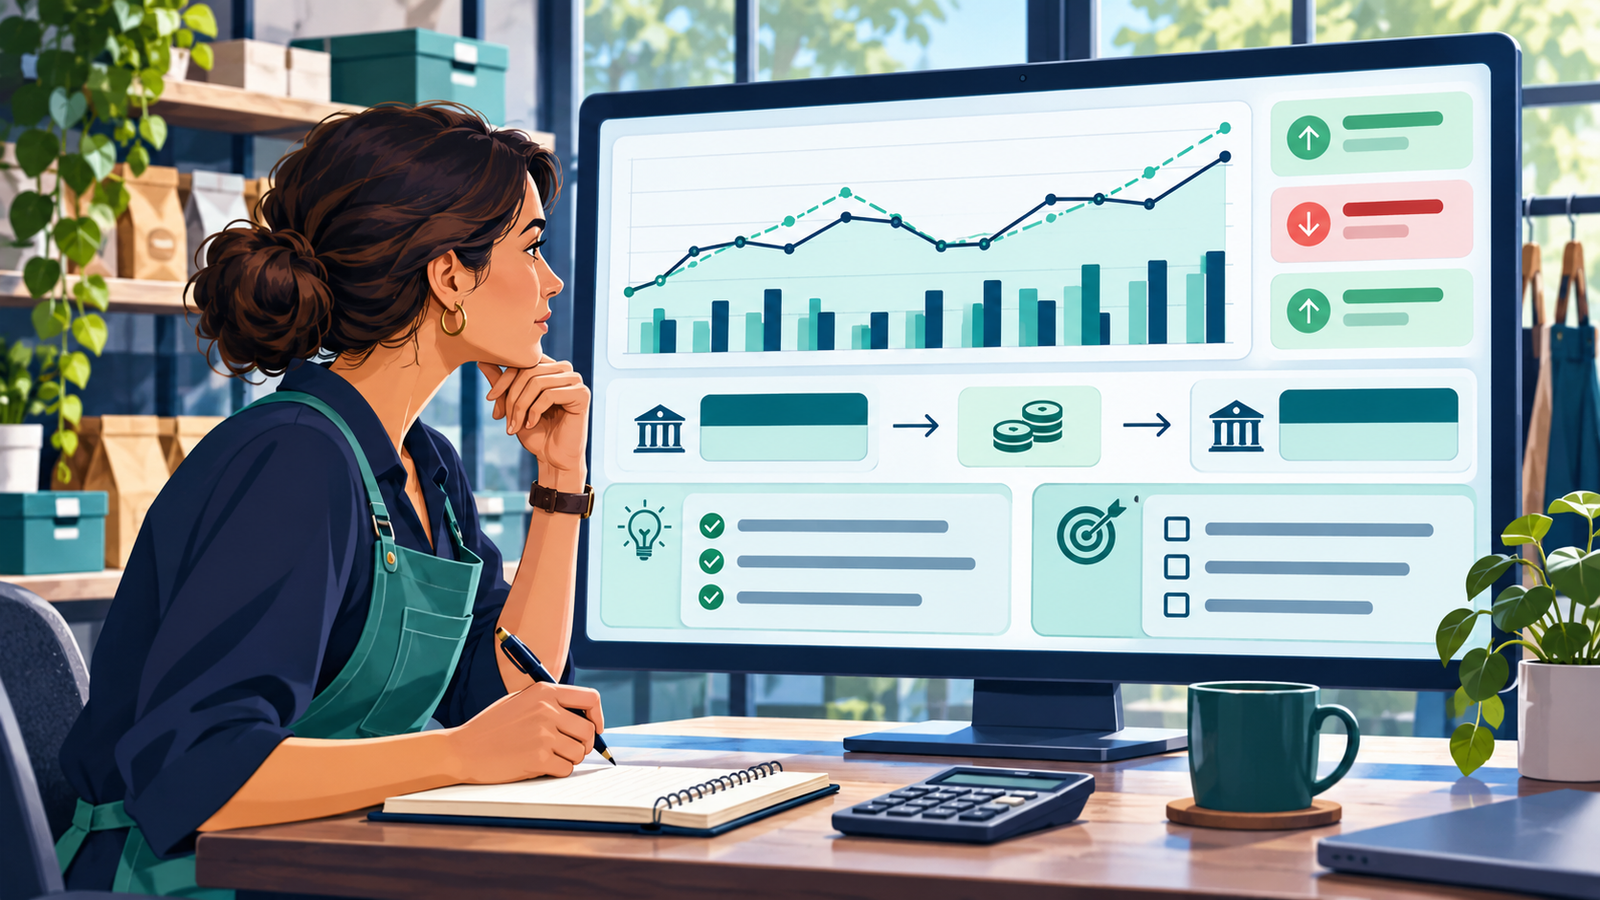
Direct answer: Compare forecast and actual cash by using the same period and categories, reconciling actual bank movements, explaining timing and permanent variances, updating assumptions, and assigning actions. A variance is useful only when its cause and next decision are recorded.
This general guide is for Australian small-business owners, including Epping, Melbourne and Victoria. Confirm current rules and software settings for your circumstances.
How should periods and categories be aligned?
Use the same opening cash, date range and categories for both views. Separate operating, investing, financing and owner movements where useful.
What must be reconciled before comparison?
Reconcile actual bank accounts and identify transfers so cash is not counted twice. Confirm the closing cash agrees with reliable records.
Which variances need explanation?
Review material sales receipts, customer timing, supplier payments, payroll, tax, finance and one-off items. Distinguish timing shifts from changes that alter the full-year outlook.
How should assumptions be updated?
Change only assumptions supported by new evidence. Record the old value, reason, owner and date so the forecast history remains understandable.
What actions should follow?
Assign collection, spending, payment-timing or funding actions with dates. Reforecast when a material assumption changes and review results again.
What belongs in the practical checklist?
- Same period and opening cash
- Actual bank movement reconciled
- Transfers excluded from double count
- Material variances explained
- Timing versus permanent split
- Assumptions versioned
- Actions and owners assigned
- Next review scheduled
What could this look like in practice?
Hypothetical example: A hypothetical Victorian agency receives a major customer payment two weeks late. The monthly variance is negative, but the quarter total is unchanged. The owner updates timing and collection actions, not annual sales. This is invented, not a client outcome.
What do business owners ask?
Is a cash-flow forecast the same as a profit forecast?
No. Cash timing differs from revenue and expense recognition.
Should every small variance change the forecast?
No. Apply a documented materiality rule and focus on decision-relevant differences.
How often should actuals be compared?
Use a cadence that fits cash risk and reporting needs, and review sooner when conditions change.
Where can you continue?
Read the live parent guide, review service information, use the related cash-flow forecasting guide, and explore the TNS Accounting homepage.
Which official sources were checked?
- Australian Government: set up a cash-flow statement
- Australian Government: create a budget
- Australian Government: manage cash flow
Published by TNS Accounting. Official sources checked 22 November 2026. Rules, guidance and software features can change; confirm the linked sources before acting.